

Prepaid corporate cards run on money you load first, so there's no credit line, no interest, and no credit check, with tidier records at tax time.
- Prepaid corporate cards help businesses control employee spending before purchases are made.
- Employees can only spend funds that have been preloaded onto their cards.
- Compared to debit and credit cards, prepaid cards offer stronger budget controls.
- Look beyond the card by comparing spend controls, virtual cards, integrations, and pricing.
- The best prepaid corporate card depends on your business's spending and expense management needs.
Business spending starts at zero and somehow keeps growing.
One software subscription turns into five. One employee card turns into twenty. And in no time, your expenses pile up, making you want to know who's spending what and how much.
That's exactly where prepaid corporate cards in the UAE come in.
Prepaid Corporate Cards give businesses more control over employee spending without relying on reimbursements, shared company cards, or endless approval chains.
But here's where things get confusing: prepaid, debit, charge, and corporate credit cards all sound like they do the same thing. But in reality, all serve different purposes. That's why choosing the right card depends not on how fancy the card looks but on how your business wants to manage spending.
This guide explains what prepaid corporate cards are, how they work, how they compare with other business payment cards, and what to consider before choosing one for your business.
What is a prepaid corporate card?
A prepaid corporate card is a business payment card that lets companies load funds onto a card before it's used. In other words, employees can spend only what's been allocated to them, so there are no surprises at the end of the month.
Think of it as setting the spending limit before the purchase happens, not after.
Let's say your marketing team is attending an exhibition in Dubai.
Instead of asking everyone to pay out of pocket and submit expense claims later, you preload each employee's corporate card with a fixed travel budget. They can use it for approved expenses like hotel stays, taxis, or client meals until the balance runs out.
Since the money is loaded onto the card in advance, there's no borrowing involved. More importantly, employees can't spend beyond the budget you've already approved.
So, here's the big question: do you need a prepaid corporate card?
Prepaid corporate cards offer multiple benefits. For startups and small businesses, they're, in fact, an easy way to introduce spending controls without opening multiple bank accounts or dealing with endless reimbursement paperwork.
You may want to consider getting one if you are struggling to manage expenses that are commonly made for:
- Employee travel expenses
- Marketing and advertising spend
- Office supplies
- Project-specific budgets
- Petty cash replacement
- Vendor payments
- Employee allowances
How do prepaid corporate cards work?
Prepaid corporate cards are simple to use. Here's how they typically work:
- Funds are loaded in advance: Businesses transfer money to individual employee cards or a central company wallet before any spending happens.
- Spending limits are set upfront: Finance teams decide who gets a card, how much they can spend, and, depending on the provider, where the card can be used.
- Employees pay for approved business expenses: Employees use the card just like any other business payment card, with transactions deducted from the available balance instead of creating debt.
- Every transaction is visible in real time: Finance teams can track spending as they happen, review receipts, and ensure purchases comply with company policies.
- Budgets can be adjusted anytime: When funds run low, or business needs change, cards can be topped up or spending limits updated in just a few clicks.
Many modern fintech platforms take this a step further by combining prepaid corporate cards with spend management software. That means a single dashboard can issue virtual cards instantly, automate approvals, collect receipts, and sync expenses with your accounting system.
Prepaid vs debit vs credit vs charge cards: What's the difference?
Business payment options have come a long way in the past few years. In fact, according to Worldpay's 2024 Global Payments Report, prepaid card transactions are expected to surpass US$1 trillion globally for the first time.
With so many payment options available, it's easy to see why businesses get confused. Should you choose a prepaid card, a debit card, a charge card, or a corporate credit card? After all, they all sound almost the same.
But here's the thing: while they all let you pay for business expenses, they work very differently. Let's explore each of these options.
| Feature | Prepaid Corporate Card | Business Debit Card | Corporate Credit Card | Corporate Charge Card |
|---|---|---|---|---|
| Source of funds | Preloaded company funds | Business bank account | Credit line from the issuer | Credit line, paid in full each billing cycle |
| Can you spend beyond available funds? | No | No | Yes, up to your credit limit | Yes, subject to issuer approval |
| Requires a credit check? | Usually no or limited | No | Yes | Yes |
| Best for | Budget-controlled employee spending | Everyday business banking | Managing short-term cash flow | Businesses with high monthly spending and strong cash flow |
| Risk of overspending | Low | Moderate | Higher | Higher |
| Employee spending controls | Strong | Limited | Varies by provider | Varies by provider |
So, is a prepaid corporate card right for your business?
This question leads to another one: what are you trying to solve?
If you're looking to keep employee spending on budget, cut down on reimbursements, and give finance teams better visibility, a prepaid corporate card is a great place to start.
However, if cash flow is your bigger concern, a corporate credit or charge card may be a better fit. And if only a few people handle business purchases, a business debit card might be all you need.
If you decide to go with a prepaid corporate card, don't just compare the card. You should compare what comes with the card. After all, the best provider is not only offering you a way to make payments. It is helping you manage your business spending.
Here's what you should look for before getting yourself a corporate card:
Spending controls
Giving employees a payment card shouldn't mean giving up visibility into company spending.
Look for features like:
- Individual spending limits
- Merchant category restrictions
- Transaction limits
- Department or project-wise budgets
- Card freezing and instant blocking
Virtual and physical cards
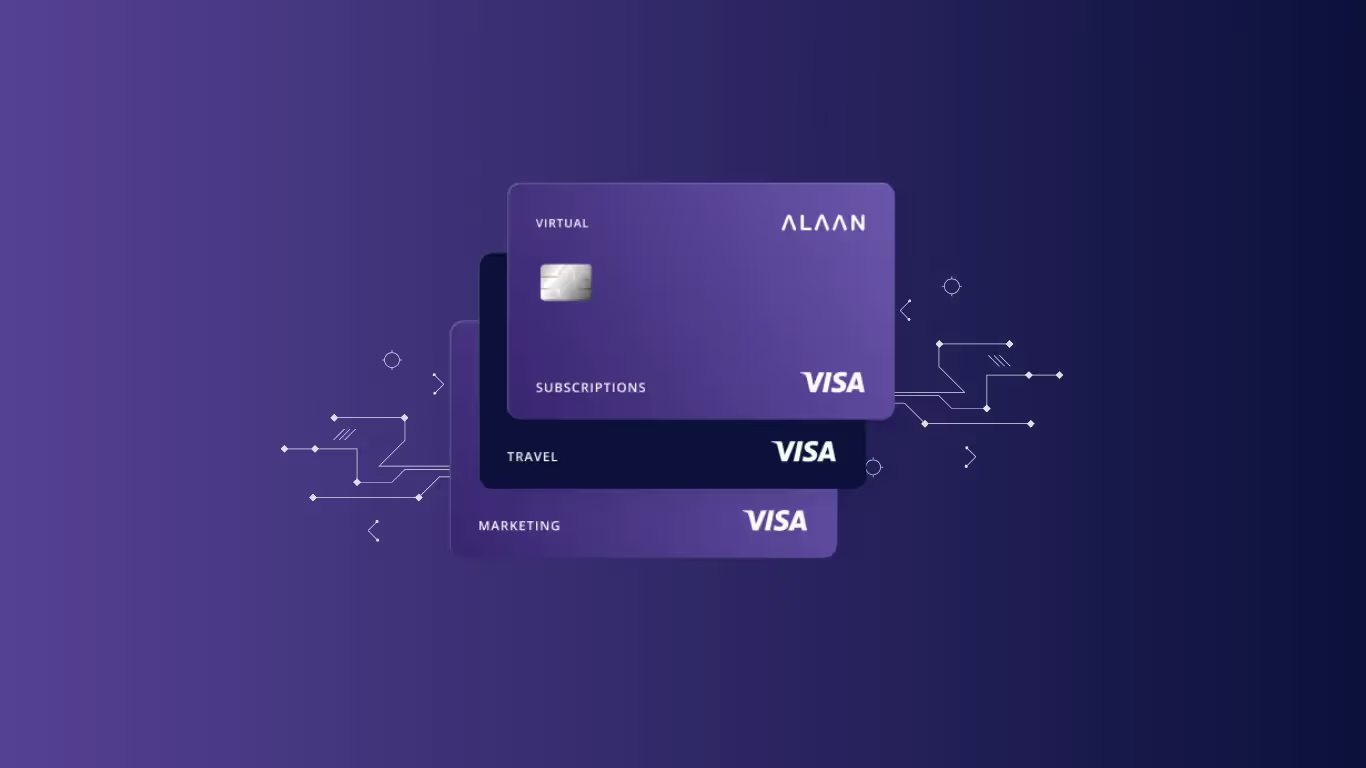
Most providers offer both physical and virtual corporate cards. Having access to both gives businesses more flexibility.
| Virtual cards for | Physical cards for |
|---|---|
| Software subscriptions | Business travel |
| Online advertising | Client meetings |
| Vendor payments | Office purchases |
| One-time purchases | In-person supplier payments |
Real-time expense tracking
One of the biggest frustrations for finance teams isn't making payments. It's figuring out what those payments were for weeks later.
Modern prepaid corporate card platforms automatically record transactions as they happen, allowing employees to upload receipts immediately while finance teams monitor spending in real time.
Accounting integrations
If your finance team already uses accounting software, the first thing you should do is check whether your card provider integrates with it. Automated transaction syncing can reduce manual data entry and speed up month-end closing.
Pricing and fees
Prepaid corporate cards can come with various fees. Some charge a monthly platform fee, while others charge for individual cards or for specific services.
Once you understand their pricing structure, you are saving yourself from unexpected costs later, which include:
- Card issuance fees
- Monthly platform fees
- Foreign exchange (FX) markups
- ATM withdrawal charges
- Card replacement fees
When comparing providers, consider both the price and the value. Features like automated expense management and accounting integrations can save far more in time than they cost in subscription fees.
Regulation, compliance, and security: What to check
Before choosing a prepaid corporate card provider, make sure it meets the following standards:
| Standards | What does it mean? |
|---|---|
| CBUAE regulation | Check whether the provider is regulated by the Central Bank of the UAE (CBUAE) or partners with a regulated financial institution where required. |
| KYC verification | Business verification helps prevent fraud and ensures the provider complies with UAE Know Your Customer (KYC) requirements. |
| VAT-ready expense management | Features like receipt capture, VAT-ready reports, and accounting integrations can simplify VAT record-keeping and filing. |
| Fraud protection | Look for instant card freezing, transaction alerts, spending controls, and virtual cards to reduce the risk of unauthorized spending. |
| Payment security | Check whether the provider follows recognized payment security standards, such as PCI DSS, to help protect cardholder data. |
Who can apply for a prepaid corporate card in the UAE?
Most prepaid corporate card providers are available to registered businesses in the UAE. While eligibility varies by provider, you'll typically need:
- A valid UAE trade license.
- Company incorporation documents.
- Emirates ID or passport of authorized signatories.
- Any additional documents required as part of the Know Your Customer (KYC) verification.
How to apply for a prepaid corporate card
The application process is pretty simple. Here's how you can apply:
- Choose a provider that fits your business needs.
- Submit your business and identity documents for verification.
- Complete the provider's KYC checks.
- As you get approved, fund your company wallet or prepaid cards.
- Issue physical or virtual cards and assign spending limits to employees.
Depending on the provider, approval can take anywhere from a few hours to a few business days. Post-approval, the next thing you should know is how to top up your card.
Unlike credit cards, prepaid corporate cards need to be funded before they can be used. Most providers allow businesses to transfer funds to a central company wallet or directly to employees' cards.
Best prepaid corporate cards in the UAE
No corporate card is the right card if you don't know what you want to do with that card.
The best choice that's why depends on how your business manages spending, approvals, and expenses.
To compare the best prepaid corporate cards in the UAE, let us evaluate them based on the factors that matter most to businesses: spend controls, virtual cards, approval workflows, real-time expense tracking, accounting integrations, and overall suitability for different business needs.
Here's how some of the most popular prepaid corporate card providers compare.
| Provider | Best suited for | Spend Management | Virtual Cards | Accounting Integration | Approval Workflows |
|---|---|---|---|---|---|
| Alaan SuperCard | Startups and growing businesses | Custom limits, merchant/category controls and real-time tracking | Unlimited virtual cards | Integrates with accounting tools including QuickBooks, Xero, Odoo and NetSuite | Custom approval workflows and spend controls |
| Emirates NBD | SMEs and corporate businesses | Spend controls, expense tracking and predefined limits | Virtual cards with predefined limits | Expense data and categorisation; integration varies by solution | Built-in admin approval flows and card request approvals |
| Mashreq Corporate Card | SMEs and larger corporates | Employee spending controls with monthly limits and merchant-category restrictions | Available through corporate card solutions; specific virtual-card capability should be verified by the product | Expense reporting and reconciliation through Visa Spend Clarity; specific accounting integrations not stated | Approval capabilities available through Mashreq business banking; product-specific expense approval controls should be verified |
| Wio Business | Digital-first SMEs and growing businesses | Real-time expense and budget tracking with individual spending limits | Multiple virtual cards with individual spending limits | Integrates with Fiskl, Wafeq, Zoho and Xero | Not a core feature: Assign approvers and set which tasks require approval |
| ADCB Corporate Cards | Mid-sized and large businesses | Expense management tools, spending limits and card controls | Single-use corporate virtual cards available | ERP integration and reconciliation support available on selected products | Dual-level approval available for ADCB Virtual Corporate Credit Card |
| KamelPay | UAE micro-SMEs and businesses managing employee expenses | Centiv combines expense management, invoices, spending decisions and reconciliation | Centiv prepaid Mastercard; virtual-card availability is not clearly stated on KamelPay's website | Not publicly specified on KamelPay's website | Integrates expenses, invoices, approvals and spending decisions into one workflow |
| Nqoodlet | Saudi micro-businesses, SMEs and larger companies | Real-time spend tracking; customizable card limits; department, project and vendor budgets; merchant/category controls; automatic invoice matching | 12 virtual cards on Starter, 20 per currency on Growth, 60 per currency on Scale and unlimited on Enterprise; physical cards also available | No direct accounting integrations currently; data can be exported to Excel. Custom accounting integrations are available on Enterprise | Real-time approval of money, card and payment requests; configurable spending policies and approval controls; Enterprise adds custom policies |
| Xpence | UAE freelancers, startups, SMEs and corporates | Real-time spend tracking; individual card limits; 500,000+ control combinations; max-balance controls; online, international and ATM-spend controls; receipt capture; auto-categorisation | Unlimited virtual cards; instant issuance; single-use virtual cards; individual limits and controls; cards can be assigned to employees, subscriptions or one-off online payments | Third-party accounting integration with transaction export; integrations with accounting tools are being built. | Real-time approval of employee fund requests; managers can approve requests and instantly top up cards; flexible approvals with automated bookkeeping |
*Comparison is based on publicly available product information at the time of writing. **Features may vary depending on the product or account type.
Beyond the card: Why Alaan SuperCard stands out
A prepaid corporate card helps control spending before a purchase is made. But that's only half the job. The other half is collecting receipts, approving expenses, and closing the books.
But don't all companies want to chase growth and not paperwork?
That's where Alaan SuperCard is different. Instead of offering just a corporate card, it combines cards with built-in spend management, so finance teams can do all that we discussed before. Let's find out what an Alaan SuperCard can do for you:
- Issue unlimited physical and virtual cards in minutes.
- Set spending limits and approval workflows.
- Track transactions in real time.
- Collect receipts automatically.
- Sync expenses with accounting software.
- Earn 2% cashback on every eligible business spending.
If you're evaluating prepaid corporate cards in the UAE, look beyond the card itself. Alaan SuperCard gives your business the tools to control spending from the moment a card is issued through expense reconciliation.
For a real example of the switch, Calo's move away from bank prepaid cards shows what changed once they had digital reports, card limits and spend they could actually see as it happened.
And if you're still weighing prepaid against other options, our explainer on how corporate cards work in general covers the wider card picture and how to choose a provider.
FAQs
1. What makes Alaan different from other corporate card solutions?
Alaan is designed specifically for businesses in the UAE. It offers unlimited corporate cards with flexible spend controls and AI-powered automation. Alaan also offers seamless integration with popular accounting tools and a strong focus on VAT compliance.
2. Does Alaan offer real-time visibility into expenses?
Yes, Alaan gives businesses real-time insights into spending, so you can see expenses in real time. This helps make smarter financial decisions and maintain better control over cash flow.
3. How do corporate card solutions help with VAT compliance in the UAE?
Corporate card solutions automatically capture VAT details from receipts and generate VAT-compliant reports in accordance with the UAE Federal Tax Authority (FTA) standards. This automation simplifies VAT filing and ensures your business stays compliant.
4. How can businesses manage travel expenses effectively?
Businesses can automate approval workflows, track travel spending, and manage reimbursements efficiently by integrating travel and expense management systems. This makes it easier to control travel budgets, reduce discrepancies, and simplify reporting.
5. What role do corporate cards play in expense management?
Corporate cards give businesses better control over employee spending by allowing limits to be set and tracked in real time. When integrated with expense management software, they automate transaction tracking, simplify expense reporting, and improve overall financial control.
6. Should I choose a fintech provider or a traditional bank for a prepaid corporate card in the UAE?
It depends on your business needs. Traditional banks typically offer prepaid corporate cards as part of their business banking services, while fintech providers often combine cards with features like spend controls, virtual cards, expense tracking, and accounting integrations. If managing business spend is a priority, a fintech solution may offer more flexibility.
Gain control over business expenses with Alaan corporate cards
Invygo earned AED 100,000 in cashback using Alaan cards
Personalise approval workflows to align with your business needs with Alaan's Spend Management platform
Discover the power of automated expense tracking and smarter spend control with Alaan
Turn data into actionable insights with Alaan's spend management tools
Stay Tax Compliant with UAE's #1 Corporate Card and Spend Management Platform
Customisable corporate card policy template
Know how much Corporate Tax you have to pay this fiscal year
Easily integrate Alaan with your ERP for accurate, real-time expense tracking
Close books faster with Alaan's AI-powered accounting automation
Reconcile your books in minutes instead of hours, every single month.
Keep petty cash organized with Alaan corporate cards and automated expense management